Home Blog Page 3

Are You the Bottleneck in Your Business?

0

Are You the Bottleneck in Your Business?

Many founders unknowingly become the biggest obstacle to their company’s growth. Join us and guest speaker Barry Cryan to discuss how to let go, build stronger teams, and create a business that can scale beyond you.

https://www.clubhouse.com/i/are-you-the-bottleneck-in-your-business/qvf9yMoy

Open Mic: Who is Winning the AI Race: Big Corps or Startups?

0

Open Mic: Who is Winning the AI Race: Big Corps or Startups?

https://www.clubhouse.com/i/open-mic-who-is-winning-the-ai-race-big-corps-or-startups/AbRPvstb

The Hidden Cost of Playing it Safe in Business

0

Is playing it safe costing your business? We’re speaking with Steve Rolle, investor and entrepreneur, to learn when to scale back, and when to take the leap.

Can You Build a Moat Around Your Idea in an AI World?

0

Adapted from Chapter 6 of Colin C. Campbell’s Start. Scale. Exit. Repeat. for the AI era.

AI has made it incredibly easy to start a company.

It has also made it incredibly easy to copy one.

A competitor can study your website, recreate features, generate similar content, launch ads, build software, and enter your market faster and cheaper than ever before.

That changes the question entrepreneurs need to ask.

It’s no longer just: Can I build this?

It’s: If this works, what stops someone else from building it too?

That’s your moat.

A Great Idea Is Not Enough

In Start. Scale. Exit. Repeat., I talk about building a moat around your business the same way you would protect a castle.

The stronger the business becomes, the more people will want a piece of it.

In the AI era, those walls need to be even stronger.

Technology itself is becoming less defensible. Features that once required a team of developers and months of work can now be replicated surprisingly quickly.

Your advantage has to come from something deeper.

Brand. Distribution. Data. Intellectual property. Customer relationships. Network effects. Exclusive partnerships. Community. Expertise.

Ideally, several of them working together.

Brand Can Become a Moat

One of the simplest moats we built was Paw.com.

The company originally operated as Treat-a-Dog, selling premium dog beds and blankets. We later invested in acquiring Paw.com.

It wasn’t cheap.

But it transformed the business.

The domain gave us a short, memorable brand that immediately communicated what we were about. In the year following the rebrand, the business more than doubled in sales and profitability.

Today, that lesson may be even more important.

When AI can generate hundreds of competing brands overnight, being remembered matters.

A great domain, recognizable brand, trusted voice, loyal audience, and strong reputation are assets a competitor cannot simply prompt into existence.

Own Something AI Can’t Easily Replicate

Founders should also ask a more difficult question:

What do we own?

That might mean patents, trademarks, copyrights, proprietary technology, exclusive contracts, unique datasets, or specialized processes.

AI can reproduce a feature.

It cannot automatically reproduce years of proprietary customer data, an exclusive licensing agreement, a trusted community, or intellectual property you legally control.

With Paw.com, for example, we pursued design and utility patents where possible. Those protections made copying our products harder.

The goal isn’t to make competition impossible.

It’s to make competing with you harder.

Distribution May Be Your Strongest Moat

At Hostopia, we learned this lesson the hard way.

We initially tried selling web hosting directly to small businesses. The problem was that we were entering a crowded market against companies with far more established customer acquisition engines.

So we changed the model.

Instead of fighting telecom companies and hosting providers, we began powering their services behind the scenes.

Our competitors became our customers.

That distribution strategy helped turn Hostopia into the gold standard in its market and ultimately contributed to the premium valuation we received when the company was sold.

The same opportunity exists today.

Thousands of companies may have access to the same AI models.

They do not have access to the same distribution.

If you control the audience, partnerships, sales channels, community, or customer relationships, the technology underneath the product becomes only one piece of your advantage.

Sometimes a Smaller Market Creates a Bigger Moat

Entrepreneurs love massive markets.

Investors do too.

But massive markets attract massive competition.

Sometimes the smarter strategy is to dominate a smaller category.

When we launched .CLUB, we had something extremely powerful: exclusivity. We held the rights to the .club domain extension. Google couldn’t create another one. Amazon couldn’t outspend us and take it away.

We had infinite digital inventory combined with a protected position.

AI founders should think the same way.

Instead of asking, How can I get 1 percent of this enormous market? ask:

What specific category could we become known for?

Being the dominant company in a valuable niche can create far more defensibility than being another small player in a gigantic market.

Give Your Idea a Defensibility Score

Before committing serious time and capital to an idea, rate its defensibility from 1 to 5.

1: I have no clear moat.

2: I know how I could build one, but haven’t started.

3: I’ve taken at least one meaningful action to protect the business.

4: I have multiple layers of defensibility.

5: Competitors would have a very difficult time replicating our position.

Then ask yourself what would move the business up one level.

Maybe it’s acquiring the right domain.

Maybe it’s filing a trademark.

Maybe it’s building proprietary data.

Maybe it’s signing an exclusive distribution agreement.

Maybe it’s creating a community competitors can’t easily recreate.

The important thing is to start building the moat before you desperately need it.

In an AI World, Build What Gets Stronger Over Time

AI will continue lowering the cost of creating products, content, software, and companies.

That’s an incredible opportunity for entrepreneurs.

But lower barriers to entry work both ways.

The companies that win won’t simply be the ones that use AI best. They’ll be the ones that use AI to move faster while building assets that become increasingly difficult to copy.

Build the product.

Build the brand.

Own the customer relationship.

Control distribution.

Protect what you can.

And keep widening the moat.

Because if you build something worth scaling, eventually someone else is going to want your castle.

Pick a Business Idea That Can Scale: A Guide for Entrepreneurs

0

A great business idea isn’t just about what you can start. It’s about what you can grow.

Entrepreneurs naturally spend a lot of time thinking about the first stage of a business: Is there a market? Can I get customers? How much money will I need? Can I actually pull this off?

But there’s another question worth asking before you commit years of your life to an idea:

What happens if this works?

That’s the central lesson from Chapter 5 of Start. Scale. Exit. Repeat.: Pick an idea that can scale—or at least understand exactly what scaling your idea will require.

Small Doesn’t Necessarily Mean Easy

There’s a common assumption that running a small business is easier than running a large one. That isn’t necessarily true.

Every business comes with challenges, and some small businesses can be surprisingly difficult to grow because their revenue is directly tied to physical space, people, or the founder’s time.

Colin uses the Montessori school he owns with his wife as an example. The school has capacity for 110 students. Once those seats are filled, adding even one more student isn’t as simple as selling another product or adding another account.

Expanding could mean buying neighboring property, getting municipal approvals, renovating or constructing a building, buying equipment, and hiring additional staff. Suddenly, going from 110 students to 111 could require an enormous capital investment.

The school can be a successful business without expanding. But its structure creates a natural ceiling.

Restaurants, gyms, retail stores, medical offices, and many other brick-and-mortar businesses face similar challenges. Growth often requires another location, additional employees, more equipment, and more capital.

That doesn’t make them bad businesses. It simply means entrepreneurs need to understand what they’re signing up for.

Scaling Is a Choice

Not every entrepreneur wants to build a massive company.

A profitable business that provides a great lifestyle, financial security, and control over your time can be an incredible outcome. In Colin’s case, his wife is perfectly happy with the Montessori school at its current size. She doesn’t want another location or a much larger operation.

There’s nothing wrong with that.

The important thing is recognizing that scaling—or choosing not to scale—is a decision.

Your business should support the life you want to build.

Before pursuing an idea, ask yourself:

  • How large do I actually want this business to become?
  • How much of my time am I willing to give it?
  • How much capital will expansion require?
  • Will growth require significantly more employees?
  • Does every new dollar of revenue create significantly more cost?
  • Can the business eventually grow without depending entirely on me?

Those questions can completely change how attractive an idea looks.

Rate the Scalability of Your Idea

One practical way to evaluate an opportunity is to give it a scalability score from 1 to 5, with 1 representing a business that is extremely difficult to scale and 5 representing one with significant scaling potential.

A rough framework looks like this:

1 — Brick-and-mortar businesses
Think schools, restaurants, retail stores, and medical offices. Growth is constrained by physical capacity, location, staffing, and high fixed costs.

2 — Time-and-materials businesses
Consulting firms, agencies, and service providers fall into this category. Revenue can grow, but usually by adding more people and more billable hours.

3 — Product or service businesses
E-commerce and online training businesses can reach larger markets, but inventory, production, financing, and fulfillment can create constraints.

4 — Recurring-revenue businesses
Subscription businesses, accounting software, and cloud services have strong scaling potential because customers continue generating revenue over time. However, building the product, retaining customers, and competing effectively can require substantial investment.

5 — Digital businesses
SaaS, domain registries, AI-driven businesses, and other digital models can potentially serve enormous markets without physical expansion for every incremental customer. The opportunity can be huge—but so can the competition.

The point isn’t that everyone should only pursue a 5.

The point is to know your number before you build.

Two Tech Companies, Two Very Different Outcomes

Colin illustrates this distinction through two companies he helped build: Brisk Mobile and .CLUB Domains.

Both were technology businesses. Both needed talented people. Both required startup capital.

But their scalability was dramatically different.

Brisk Mobile operated using a time-and-materials consulting model. More revenue generally meant winning more contracts and having more skilled people available to complete the work. People and time were directly connected to growth.

Colin rates that model around a 2 out of 5 for scalability.

.CLUB Domains was fundamentally different. It could sell domain registrations through a worldwide marketplace, and a relatively small team could support a much larger revenue base. During the period Colin owned the company, nearly a million domains were registered.

That earns the model a 5 out of 5 on his scalability index.

The distinction highlights one of the most important questions entrepreneurs can ask:

What has to increase when my revenue increases?

If doubling revenue requires roughly doubling your employees, office space, equipment, and management complexity, scaling is going to be difficult.

If revenue can multiply without expenses increasing at the same rate, you may have something much more scalable.

Scalability Creates Leverage

The best scalable businesses have leverage built into their model.

Build software once, and potentially thousands—or millions—of customers can use it.

Create a digital product once, and it can be sold repeatedly.

Build recurring revenue, and existing customers can continue producing revenue while you acquire new ones.

That leverage can create higher margins and dramatically increase the potential value of the company.

It can also make a business more attractive to investors and eventual acquirers because they’re not simply buying today’s revenue. They’re buying a system capable of generating substantially more revenue tomorrow.

But More Scalability Can Mean More Risk

There’s another side to the equation.

A highly scalable business can access a much larger market, but so can its competitors.

A local restaurant may compete primarily with other restaurants in its area. A digital platform could find itself competing against businesses anywhere in the world.

The larger the opportunity, the more people are likely to chase it.

Scalable companies can therefore face intense competition, copycats, aggressive pricing, rapidly changing technology, and constant pressure to defend their market position.

In other words, higher scalability can create both higher potential reward and higher potential risk.

That’s why choosing a scalable idea isn’t enough. Eventually, you also need to build something defensible.

Ask Yourself What Happens at 10X

One of the simplest exercises you can do before launching a company is to imagine that it succeeds beyond your expectations.

If you had 10 times as many customers tomorrow, what would happen?

Would you need 10 times as many employees?

Ten more locations?

A bigger warehouse?

Millions of dollars of additional equipment?

Or could your existing infrastructure handle much of that growth?

You don’t need perfect answers at the startup stage. But thinking through the question exposes the structural limitations of a business before you’ve invested years trying to overcome them.

Choose With Your Eyes Open

There is no universal rule that says every entrepreneur needs to build a massive, global company.

A single restaurant can be a great business. So can a consulting firm, medical practice, school, real estate business, or local service company.

But every business model comes with a different growth equation.

Understand that equation before you commit.

Know how much capital growth will require. Know how dependent the business will be on hiring. Know whether geography limits you. Know whether revenue is tied directly to your time. And know whether that’s compatible with the life and company you actually want to build.

Because picking an idea isn’t only about deciding what business you want to start.

It’s deciding what kind of business you want to own when it succeeds.

Key Takeaway

Don’t judge an idea only by whether it can become a business. Judge it by what has to happen for that business to become bigger.

Rate its scalability. Understand the trade-offs. Decide how much growth you actually want.

Then build accordingly.

The Exit Window Is Open. Most Founders Aren’t Ready.

0

Buyers are back. In July 2026 alone, venture-backed M&A cleared $9 billion and twelve companies went public above a billion-dollar valuation.

Most founders will miss it. Not because they don’t want to sell. Exit readiness takes eighteen to twenty-four months — every clean exit I’ve been part of did — and most founders start the week a buyer calls.

That week is the worst possible moment to begin.

Windows Close Without Announcing It

I’ve been through this cycle enough times to know its shape. Liquidity freezes. Everyone waits. Valuations hold up on paper while nothing actually sells.

One market analysis put the problem plainly this month: higher private valuations “may improve paper returns, but they do not return capital to limited partners.”

Then the ice cracks. Acquirers who hoarded cash for two years start shopping. Bankers float the next big listings — OpenAI, Anthropic, Databricks, Stripe. Crunchbase read July’s mix of billion-dollar rounds, M&A, and IPOs as an ecosystem where capital “is also beginning to recycle through exits.”

Beginning. Not finished.

That word matters, because this window will close, and it will close faster than it opened. One bad quarter, one rate surprise, one geopolitical shock, and the acquirers go quiet for another two years.

Rule: You can’t time an exit window. You can only be ready when one opens.

Exit Readiness Is the Whole Game

An exit is not an event. It’s a process that starts long before anyone makes an offer, and the founders who get clean, high-multiple outcomes did the unglamorous work years earlier.

I’ve sold companies. I’ve also sat in the room where a buyer repriced a great business downward in diligence over things that would have taken six months to fix — if anyone had started six months earlier.

Nobody hands you those six months once a process is live. Every week you spend fixing something is a week the buyer spends finding a reason to pay less.

The Exit Readiness Checklist

What has to be true before the phone rings.

1. Your books survive a stranger.

Not “my bookkeeper knows where everything is.” Clean, accrual-based financials going back three years, ideally reviewed or audited. Revenue recognized consistently. Add-backs documented and defensible.

Rule: If explaining your numbers takes more than ten minutes, your valuation is already falling.

2. No customer is worth more than 20% of revenue.

Customer concentration is the fastest way to lose a turn of multiple. A buyer sees one client at 40% of revenue and sees a company that could halve the day after closing. They price that risk aggressively.

Fixing it takes years. Start now.

3. The business runs without you for thirty days.

The hardest one, and the one founders fight. If you are the salesperson, the product decision-maker, and the person approving invoices, you aren’t selling a company. You’re selling a job — and buyers pay far less for jobs.

Test it honestly. Leave for thirty days. What breaks becomes your work list.

4. Your contracts transfer.

Go read your customer agreements. Find the change-of-control clauses that let clients walk or renegotiate on acquisition. Check your key employee agreements. Check your IP assignments, especially for anything a contractor built in the early years.

I watched a deal stall four months over one missing IP assignment from a freelancer nobody could find.

5. Your growth story has a number attached.

“We’re growing fast” is not a story. “We grew 62% year over year for three consecutive years with net revenue retention of 114%” is a story. Buyers pay more for predictability than for velocity.

6. You know your walk-away number before you enter the room.

Decide it while you’re calm. Write it down. Once a term sheet sits in front of you, excitement, exhaustion, and eight months of sunk cost wreck your judgment.

Rule: Set your floor before the adrenaline arrives.

The Mistake I See Most

Founders treat the exit as the reward for building. It isn’t. It’s a separate discipline with its own skill set, and it sits third in Start. Scale. Exit. Repeat. for a reason — between scaling and starting again, and you have to earn it deliberately.

The founders who do this well aren’t smarter. They ran the business as if it were for sale, every year, whether or not it was.

That habit has a side effect: a company built to be sold is a better company to own. Clean books, diversified revenue, a team that operates without you. None of that is exit prep. That’s just good business.

The Item You’ve Been Avoiding

Go back through those six. One of them made you flinch.

That’s the one costing you a turn of multiple, and it’s the one you’ve been deferring for two years because fixing it means an uncomfortable conversation — with your largest customer, with your accountant, with the person who shouldn’t be running your sales team anymore.

Book that conversation this week. Not the easy items. The one you skipped.

The window is open now. The work should have started two years ago.

Second best time is today.

Second-Time Founders: Repeat Is the Hardest Word

0

Six weeks after the wire hits, most founders feel nothing at all. Not relief. Not triumph. Nothing.

That’s the part of the exit nobody warns you about, and a lot of people are about to walk into it. July 2026 alone produced twelve venture-backed companies listing above a billion dollars. A cohort of second-time founders is forming right now, and most of them think the hard part is behind them.

The Exit Doesn’t Feel Like You Think It Will

You sign. The money lands. And within about six weeks the feeling you expected — relief, triumph, arrival — doesn’t arrive. What shows up instead is a flat quiet.

Not depression. Not regret. Just the absence of the thing that structured every day for years.

For a decade you woke up with a problem to solve and a team that needed you. Then one Tuesday you wake up with neither. Your calendar is empty, and it’s supposed to be a reward.

It doesn’t feel like one.

That’s not ingratitude. It’s withdrawal.

I’ve been through this cycle. I’ve talked with dozens of founders in Startup.Club sessions who have too, and the pattern repeats with unsettling consistency. The ones who struggle hardest are the ones who identified hardest with the company — the ones who, asked what they do, gave the company’s name instead of their own.

Selling the company sold the answer to that question.

Why Second-Time Founders Have It Harder

The second company should be easier. You have money, a network, a reputation, and a proven playbook.

Every one of those turns into a liability.

Money removes the constraint that made you good. The first time, you couldn’t afford to be wrong for long. Every dollar bought a test. Now you can fund a bad idea for two years, and you will, because you can.

The network gives you false validation. Your friends will tell you the idea is great. They said that about the first one too, but back then you didn’t believe them — you went and found strangers who’d pay. Now the flattery lands differently, because you earned it.

The reputation makes you slow. The first company failed in private. This one fails in public, in front of everyone who watched you win.

That fear doesn’t make you careful. It makes you avoidant. You spend nine months on strategy and zero on customers.

The playbook is the worst of them. It worked. It worked so well you sold a company. So you run it again — same channel, same pricing, same hiring sequence — and it fails, because the market moved while you were busy winning.

Rule: The playbook that got you out is not the playbook that gets you back in.

What Repeat Actually Requires

“Repeat” in Start. Scale. Exit. Repeat. does not mean do the same thing again. It means returning to beginner conditions on purpose while holding the judgment you earned.

That’s a narrow path. Here’s how to stay on it.

1. Constrain yourself artificially. Give the new company a budget it has to live inside, and hold that line as though outside money were the only option. If you’d fund it from a $500K seed, fund it from $500K — not from exit proceeds, which carry no discipline at all.

2. Go find strangers. Your first ten customers should be people who don’t know your name and don’t care about your last company. If early traction comes only from your network, you’ve proven your network is loyal. Nothing else.

3. Separate the transferable from the situational. What you actually learned was judgment: how to read a customer, when to cut a hire, what a real signal looks like next to a polite one. That travels. The tactics — the specific channel, the price point, the launch sequence — don’t.

4. Give yourself a real gap. Not a vacation. A genuine stretch with no company, long enough to notice who you are without one. Founders who start the next thing three weeks after closing are running from the quiet, and a company started as an escape is a company you won’t want to run in year three.

5. Say the hard thing out loud. To a peer group, a coach, another founder who’s been through it. The isolation after an exit is worse than the isolation during the build, because during the build you at least had a team. Afterward you have a bank balance and a lot of people who assume you’re fine.

Why It’s Still Worth Doing

None of this argues against repeating.

The founders I know who built more than once are, without exception, better the second and third time. Not because it got easier. Because they got more honest.

They cut faster. They hire better. They stop confusing motion with progress. They know which fears are signal and which are noise, and that distinction is worth more than any amount of capital.

That improvement isn’t automatic. It shows up only for founders who treat the second company as a genuinely new problem instead of a rerun.

Start is exciting. Scale is grinding. Exit is technical.

Repeat asks who you are without the thing you built.

Answer that first. Then build.

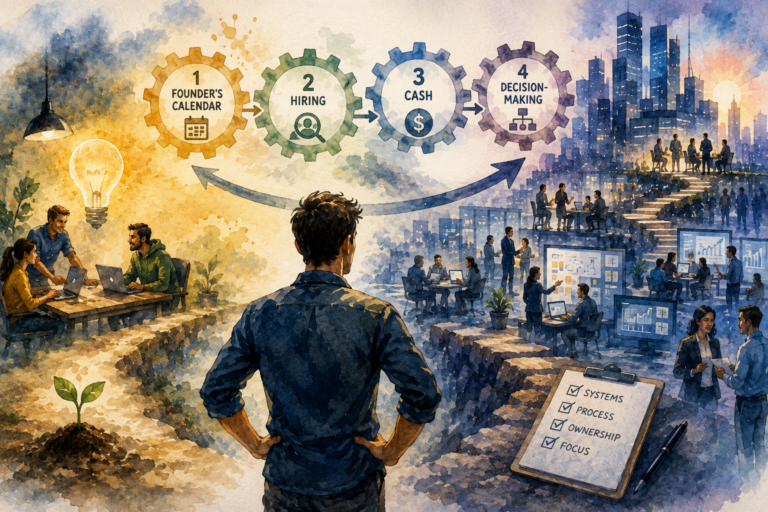
How to Scale a Startup: What Actually Breaks

0

Most companies don’t die from lack of demand. They die from getting it.

How to scale a startup is really one question: what happens when the thing that was working stops working? The cruelty of it is that nothing looks wrong from outside. Revenue is up. The team is bigger. The press is better.

Inside, four systems are failing on different timelines, and no two fail at the same moment.

Here’s what breaks, in order, and the warning sign for each.

1. The Founder’s Calendar Breaks First

It goes before anything else, and almost nobody notices, because it doesn’t feel like a system failing. It feels like being busy.

At five people you sit in every conversation and that’s an advantage. At fifteen you sit in every conversation and it’s a bottleneck. At thirty you are the reason decisions take four days, because everything routes through the one person holding context on everything.

Warning sign: your team stops bringing you problems and starts bringing you approvals. They’ve learned that deciding without you carries risk. The moment that happens, your personal throughput caps your company’s speed.

The fix isn’t delegation. It’s context transfer. Delegating a task moves work. Transferring context moves judgment, so your team makes the next twenty decisions without you.

Rule: If you’re the fastest way to get an answer, you’re the slowest part of the company.

2. Hiring Breaks Second

Your first ten hires came through your network. People you knew, or people known by people you trusted. They arrived pre-vetted, culturally aligned, and willing to do whatever the week demanded.

That well runs dry somewhere between fifteen and twenty-five people. Then you hire strangers, and the hit rate collapses.

Founders respond by hiring faster, which is exactly wrong. A bad hire at forty people doesn’t just underperform. They hire more people like themselves, and now a whole branch of the org chart doesn’t work.

Warning sign: you describe a new hire as “we’ll see how they work out.” You never said that about hire number three.

What works:

  • Write the scorecard before the job post. Five outcomes, ranked. Can’t name what success looks like in twelve months? You don’t know what you’re hiring for.
  • Let someone who isn’t you make the final call on at least one hire per quarter. It’s the only way to learn whether your standard transferred.
  • Fire in weeks, not quarters. The cost of a bad hire isn’t their salary. It’s the good people who leave because you tolerated them.

Rule: Slow to hire is not a virtue. Slow to decide is the mistake.

3. Cash Breaks Third, and Quietly

This one kills companies that were, by every other measure, succeeding.

Growth eats cash. You pay for inventory, headcount, and infrastructure before the revenue those things generate arrives. The faster you grow, the wider the gap — and profitable-on-paper businesses run out of money in the middle of their best year.

I’ve watched it happen to businesses with excellent margins and a full pipeline.

Warning sign: you check the bank balance more often than the P&L. That instinct is correct. Listen to it. Your P&L tells you a story about the past. Your cash position tells you about next month.

What to install:

  • A rolling 13-week cash forecast. Weekly, not monthly. Thirteen weeks is long enough to see a problem coming and short enough to stay accurate.
  • A hard cash floor. Pick the months of runway below which you will not go, and act at that line instead of past it.
  • Your cash conversion cycle. Days from spending a dollar to collecting the revenue that dollar produced. Shorten it by fifteen days and you’ve funded a hire.

Rule: Profit is an opinion. Cash is a fact.

4. Decision-Making Breaks Last, and Worst

The endgame failure. This is the one that turns a fast company into a permanently slow one.

Early on, decisions happen in hallways. Somebody asks, somebody answers, done. Nobody writes anything down and it works fine, because everyone shares the same context.

Past fifty people that shared context is gone. The hallway conversation now excludes six people who needed to be in it.

So meetings appear. Then meetings to prepare for meetings. Then a process to manage the meetings.

Warning sign: two groups make the same decision and reach different answers. That’s not a communication problem. That’s a missing decision structure.

What to install:

  • A single owner for every decision. Not a committee. One name.
  • A split between reversible and irreversible. Make reversible decisions fast and alone. Give irreversible ones a week and a room. Most companies do this exactly backwards.
  • The “why” written down, not just the “what.” A decision with no documented reason gets relitigated every six months by whoever wasn’t in the room.

Rule: Speed doesn’t come from working faster. It comes from deciding once.

How to Scale a Startup: Replace Proximity With Systems

Every one of those four failures has the same root cause. Something that worked because of proximity stops working when proximity disappears.

So scaling is one job: replacing proximity with systems, on purpose, before you’re forced to. That’s the whole argument of the Scale chapter in Start. Scale. Exit. Repeat., and it’s the stage where founders resist hardest, because building systems feels like bureaucracy when you’re used to speed.

It isn’t. Bureaucracy is what you get when you build the systems late, in a panic, after something already broke.

Take the four above and ask which one is currently your constraint. Not which is most broken — which is holding back everything else.

Fix that one. Then look again, because it will be a different one.

Scaling isn’t a phase you complete. It’s a bottleneck you keep moving. Just make sure you’re the one moving it, and not the last person to notice it moved.

Focus on Something You and Others Love: A Founder’s Framework for the AI Era

0

Adapted for an AI world from Chapter 4 of Colin C. Campbell’s Start. Scale. Exit. Repeat.

In 1993, I made a decision that looked questionable on paper.

My partners and I had built ComputerLink, a profitable BBS company. The business worked. It had customers. It made money.

And we decided to shut it down.

Why?

Because we could see something much bigger coming: the internet.

We loved what we had built with ComputerLink—the community, the connectivity, and the ability for technology to bring people together. But we realized that the BBS itself wasn’t the thing we loved most.

It was the idea behind it.

The internet was becoming a vastly better vehicle for that idea.

So we took the assets of a profitable company and used them to start Internet Direct, venturing into an industry that was still largely uncharted.

More than three decades later, entrepreneurs are facing a remarkably similar moment with artificial intelligence.

AI is changing how companies are built, how work gets done, and what customers expect. New tools and business models seem to appear every week.

That creates enormous opportunity.

It also creates enormous distraction.

The founders who thrive in this environment won’t necessarily be the ones who chase AI the fastest. They’ll be the ones who understand what they truly care about, what their customers care about, and how AI can become a better vehicle for delivering it.

Here is a framework for doing exactly that.

1. Separate What You Love From the Vehicle Delivering It

One of the most important lessons I’ve learned as an entrepreneur is this:

Don’t fall so deeply in love with your business that you go down with it.

Fall in love with the purpose instead.

In the early 1990s, BBS operators had built thriving businesses. When the internet arrived, some couldn’t let go. They had fallen in love with the vehicle rather than what the vehicle accomplished.

The same danger exists today.

Maybe you love your SaaS product.

Maybe you’ve spent years building a marketplace, agency, app, consulting business, or software platform.

Then AI arrives and suddenly customers can accomplish part of what your product does with a prompt.

The wrong response is to protect yesterday at all costs.

Ask instead:

What did customers actually love about what we built?

Was it the software itself?

Or did they love saving time?

Making better decisions?

Feeling more creative?

Connecting with other people?

Growing their business?

Removing frustrating work?

Once you understand that, AI stops looking purely like a threat. It can become the next vehicle for delivering the thing people already value.

That leads to the first question in the framework:

What do we love about the problem we’re solving—and is there now a better way to solve it?

2. Don’t Confuse AI Excitement With Customer Love

There’s another problem with transformational technologies: entrepreneurs want to build everything.

I know this problem well.

I’ve joked that entrepreneurship should be classified as a drug. A new idea can produce an incredible rush, and serial entrepreneurs often don’t struggle to generate ideas.

They struggle to pick one.

AI has multiplied that temptation.

Every week brings another model, agent, platform, capability, or startup category. Suddenly you can imagine dozens of businesses that weren’t technically possible a few years ago.

But possible doesn’t mean valuable.

And interesting doesn’t mean customers will care.

Instead of asking:

What can I build with AI?

Try asking:

What do people already desperately want that AI now allows me to deliver dramatically better?

That distinction matters.

Technology can create capability.

Customers create businesses.

Before committing significant time and capital to an AI opportunity, look for three overlapping signals:

Founder Love:
Would you still care about solving this problem after the novelty of the technology disappears?

Customer Love:
Do people genuinely want the outcome enough to change their behavior, recommend the product, or pay for it?

AI Leverage:
Can AI make the solution substantially faster, cheaper, easier, smarter, more personalized, or previously impossible?

The strongest opportunities sit at the intersection of all three.

Love it. Prove others love it. Then use AI to amplify it.

3. Avoid the Shiny-Object Trap

In previous technology revolutions, entrepreneurs could spend years riding a trend.

AI cycles can move much faster.

Today’s breakthrough can become tomorrow’s commodity.

That makes focus even more valuable.

When every founder can rapidly prototype ten ideas, the competitive advantage isn’t necessarily producing the eleventh.

It may be having the discipline to decide which one deserves the next ten years of your life.

Ask yourself:

If AI stopped being exciting tomorrow, would I still care deeply about this problem?

That’s a powerful filter.

Because building a meaningful company remains hard.

There will still be difficult customers.

Hiring mistakes.

Cash-flow problems.

Competitors.

Failed experiments.

Slow months.

Products that don’t work.

Strategies that have to be rewritten.

AI may accelerate parts of entrepreneurship, but it doesn’t eliminate the emotional roller coaster of building a company.

Which is why love still matters.

4. Build Something Humans Still Care About

The more capable AI becomes, the easier it is to become obsessed with what machines can do.

Founders should spend just as much time thinking about what humans want.

People still want to save time.

They still want to belong.

They want status, convenience, security, entertainment, health, wealth, connection, confidence, and meaning.

They want someone to understand their problems.

They want products that make their lives better.

Those human motivations don’t disappear because the technology underneath a business changes.

So don’t start your strategy with the model.

Start with the human.

Ask:

Whose life gets meaningfully better if we succeed?

Then ask:

How does AI allow us to improve that outcome by 10x?

That produces a very different company than simply attaching AI to an existing product because the market expects you to.

5. Make Sure the Idea Reflects Your Values

Love is difficult to quantify.

One useful way to evaluate it is through your values.

Write down the ideas you’re considering and ask what genuinely excites you about each one.

Then ask:

Does this idea reflect something I care deeply about?

If sustainability matters to you, how does the company contribute to it?

If education matters, how does the company help people learn?

If entrepreneurship matters, how does the company help founders succeed?

If you care about improving people’s lives through technology, where does that show up in the product?

This becomes especially important with AI because founders aren’t simply choosing what they can automate.

They’re choosing what they should automate—and what role they want technology to play in people’s lives.

Values can become a strategic filter.

Just because AI can do something doesn’t mean that’s the company you should spend a decade building.

6. Use Other People’s Excitement as Evidence

Loving your own idea isn’t enough.

Other people need to love it too.

Talk to potential customers. Show them prototypes. Explain the vision. Watch their reactions.

But don’t only listen to what people say.

Look at what they do.

Do they ask when they can use it?

Do they introduce you to someone else who needs it?

Do talented people want to join you?

Do potential partners start suggesting ways to help?

Most importantly:

Will customers pay?

Authentic enthusiasm has a way of spreading.

When the founder loves the mission, customers love the outcome, and talented people want to participate, you may have found something worth pursuing.

7. Let AI Change the Business Without Changing the Mission

This may be the most important lesson of all.

ComputerLink wasn’t our mission.

It was a vehicle.

When a better vehicle arrived, we moved.

Entrepreneurs in the AI era should develop the same willingness.

Your product may change.

Your interface may change.

Your pricing model may change.

Tasks that once required twenty employees may eventually require five employees working with AI agents.

Entire features may disappear.

Your competitive advantage may move from software functionality to proprietary data, distribution, community, trust, workflow integration, brand, or customer relationships.

That’s okay.

Preserve the reason the company deserves to exist. Be willing to reinvent almost everything else.

The AI Founder Love Test

Before pursuing your next idea—or deciding whether AI should transform your existing company—answer these seven questions:

  1. What do I actually love about this idea?
  2. What outcome do customers love?
  3. Would I care about this problem if AI weren’t fashionable?
  4. Does solving it reflect my values?
  5. Does AI materially improve the solution rather than merely decorate it?
  6. Are customers demonstrating love through behavior, not just compliments?
  7. Am I willing to change the vehicle while protecting the underlying mission?

If you can’t answer those questions clearly, keep exploring.

If you can, focus.

Because the abundance created by AI makes focus more important, not less.

We’re entering a period in which entrepreneurs can build more, test faster, automate more, and pursue opportunities that would have required enormous teams and capital only a few years ago.

But that doesn’t mean you should pursue all of them.

Life is still too short to spend your time, attention, and resources building something neither you nor your customers truly care about.

Find the problem you love.

Make sure other people love the outcome.

Use AI to build a dramatically better way of delivering it.

Then focus long enough to make it matter.

And once you’ve found that idea, two timeless questions remain:

Can you scale it?

And can you defend it?
The #1 Skill for the AI Age: Learn How to Learn

0

The #1 Skill for the AI Age: Learn How to Learn

https://www.clubhouse.com/i/the-1-skill-for-the-ai-age-learn-how-to-learn/npX7t2E1